Many business owners assume that every company is required to have Taxable Entrepreneur (PKP) status from the very beginning. In fact, this obligation only arises when the business has met the qualifications set forth in national tax regulations. Not a few business owners also only realize the importance of this status when potential B2B clients or government agencies require official tax invoices in tender cooperation.
PKP status is not determined by the company's age or its legal entity form. In Indonesian tax law, the main threshold for this obligation is based on the gross turnover value achieved by the business in one fiscal year.
What Is a Taxable Entrepreneur (PKP)?
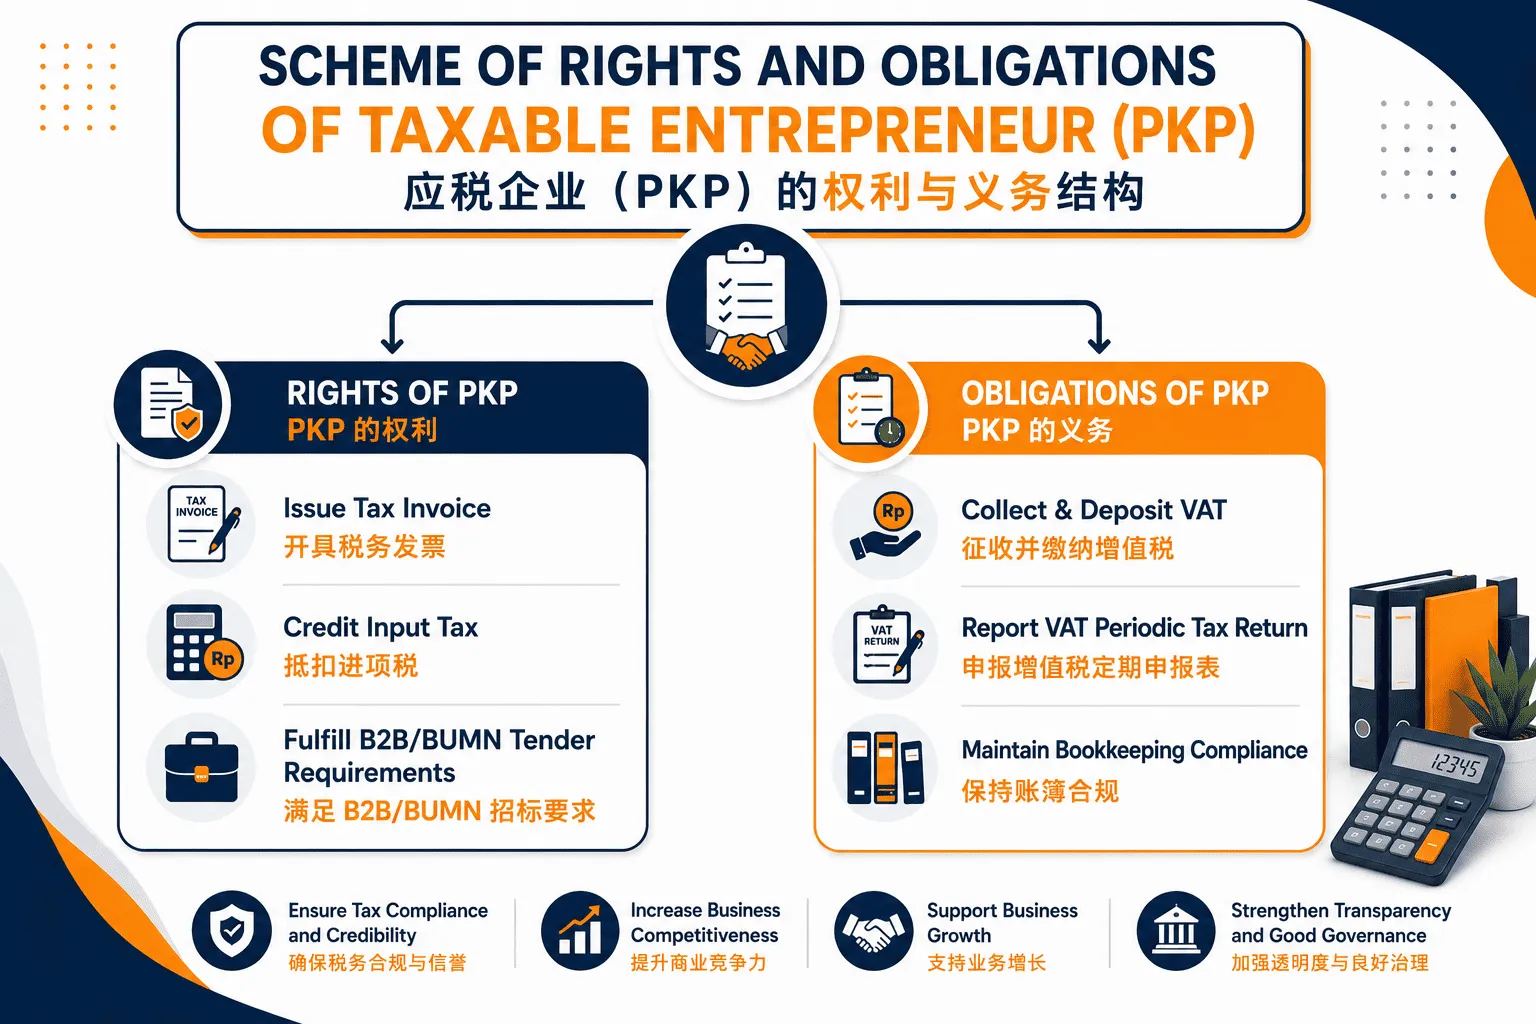
A Taxable Entrepreneur (PKP) is a business or individual that has been officially confirmed by the Directorate General of Taxes (DJP) to collect, deposit, and report Value Added Tax (VAT) and Sales Tax on Luxury Goods (PPnBM) on the delivery of Taxable Goods and Taxable Services.
PKP confirmation provides legality and strategic advantages for business development:
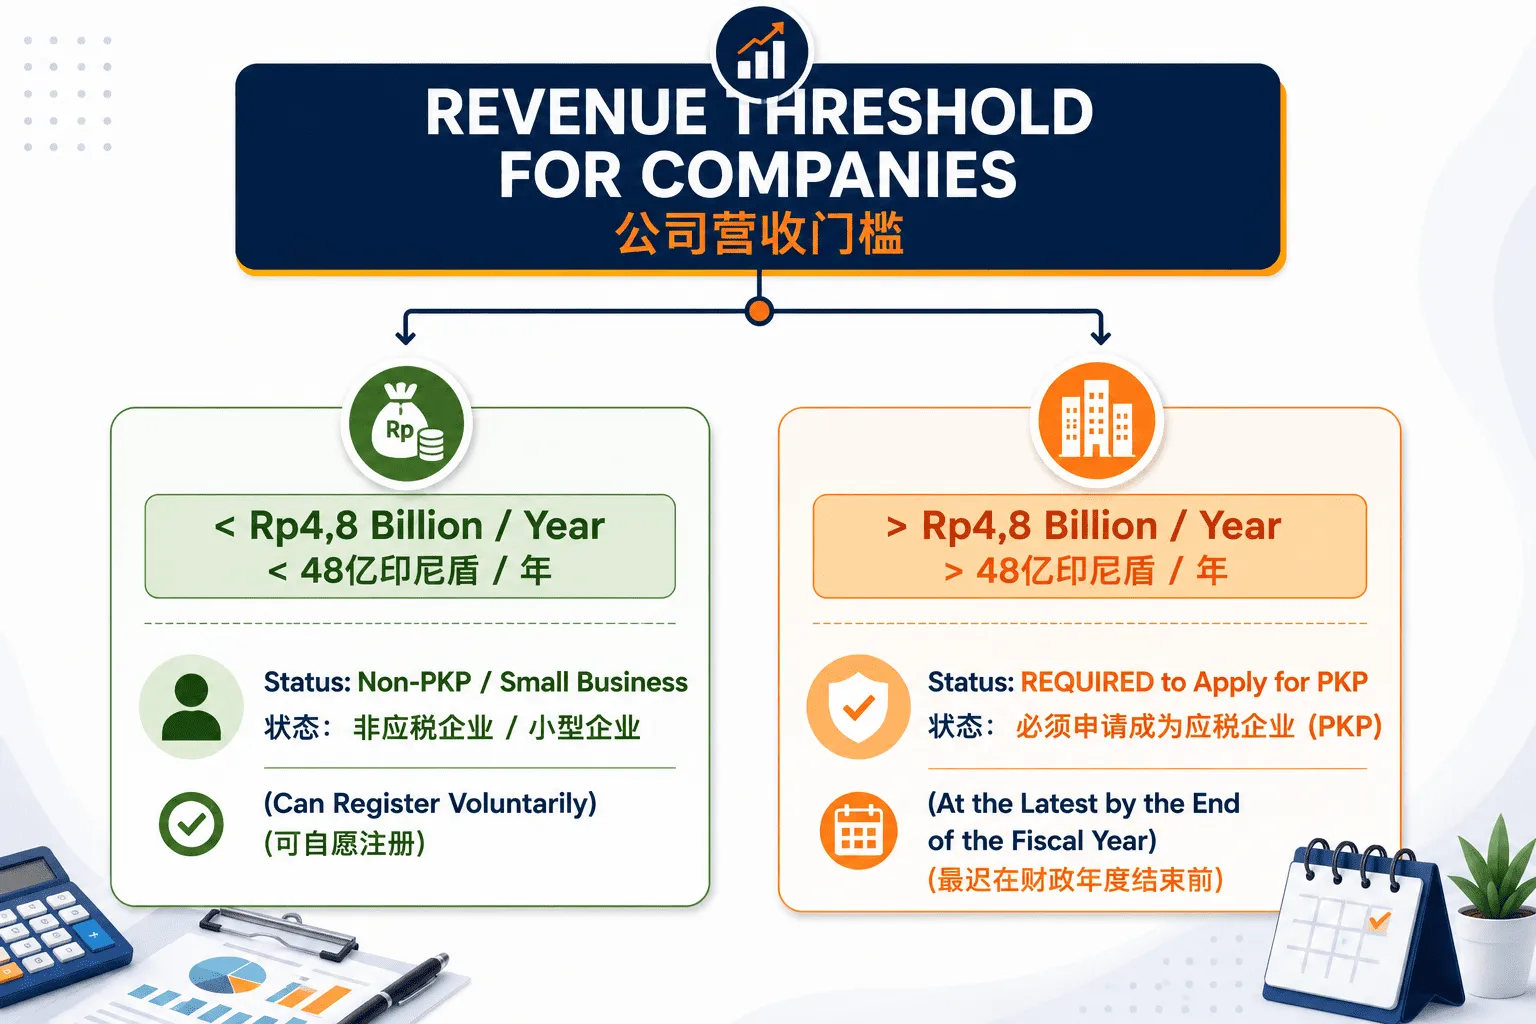
PKP Turnover Threshold: IDR 4.8 Billion per Year
The main requirement that obligates a business to become PKP is achieving a turnover exceeding IDR 4.8 billion in one fiscal year.
This provision is regulated in PMK Number 197/PMK.03/2013 and reaffirmed through implementing regulations PMK Number 164 of 2023 and PER-7/PJ/2025.
Simulation of Submission Timing and VAT Collection
Many business owners assume that VAT collection directly applies in the month when turnover reaches IDR 4.8 billion. In fact, there are administrative time stages regulated by law:
- Case Example: Your company records cumulative turnover of IDR 3.2 billion up to June, then surges to IDR 4.9 billion in July.
- Reporting Deadline: According to Article 17 paragraph (3) of PMK 164/2023, you are required to submit a PKP confirmation application no later than the end of the same fiscal year.
- VAT Collection Start: The obligation to collect, deposit, and report VAT only takes effect starting from the first Tax Period of the following fiscal year, unless you submit an application to collect VAT earlier and it is approved by the DJP.
Who Else Is Required to Become PKP Besides the Turnover Limit?
In addition to businesses with turnover exceeding IDR 4.8 billion, there are other legal subjects required to submit PKP Confirmation under PER-7/PJ/2025:
- Joint Operation (KSO): Joint Operation or KSO business entities are required to be confirmed as PKP if the consortium's turnover exceeds IDR 4.8 billion or if one of its member entities already has PKP status.
- Government Bodies or Agencies: Government entities that deliver Taxable Goods/Services in operational business activities are required to register as PKP.
Can a Business with Turnover Below IDR 4.8 Billion Become PKP?
Yes. Small business actors with gross turnover that has not yet reached IDR 4.8 billion are permitted to apply for voluntary PKP confirmation.
This voluntary step is generally taken to increase company credibility, facilitate transactions with large corporate partners, and take advantage of Input Tax credit mechanisms on initial capital goods purchases.
Risks and Legal Consequences of Late PKP Confirmation
- Ex-Officio Confirmation by DJP
If your business has met the turnover criteria but has not yet reported itself, the local Tax Office (KPP) has the authority to issue Ex-Officio PKP Confirmation based on Article 55 paragraph (1) of PER-7/PJ/2025. This assessment is based on audits of third-party data, banking data, and buyer invoice transactions. - Penalty Fines and Retroactive Tax Bills
If confirmed ex-officio, the DJP has the right to collect VAT obligations that should have been collected from the date of determination, plus administrative interest sanctions according to the Tax Law (UU KUP). This can certainly disrupt your business's operational cash flow.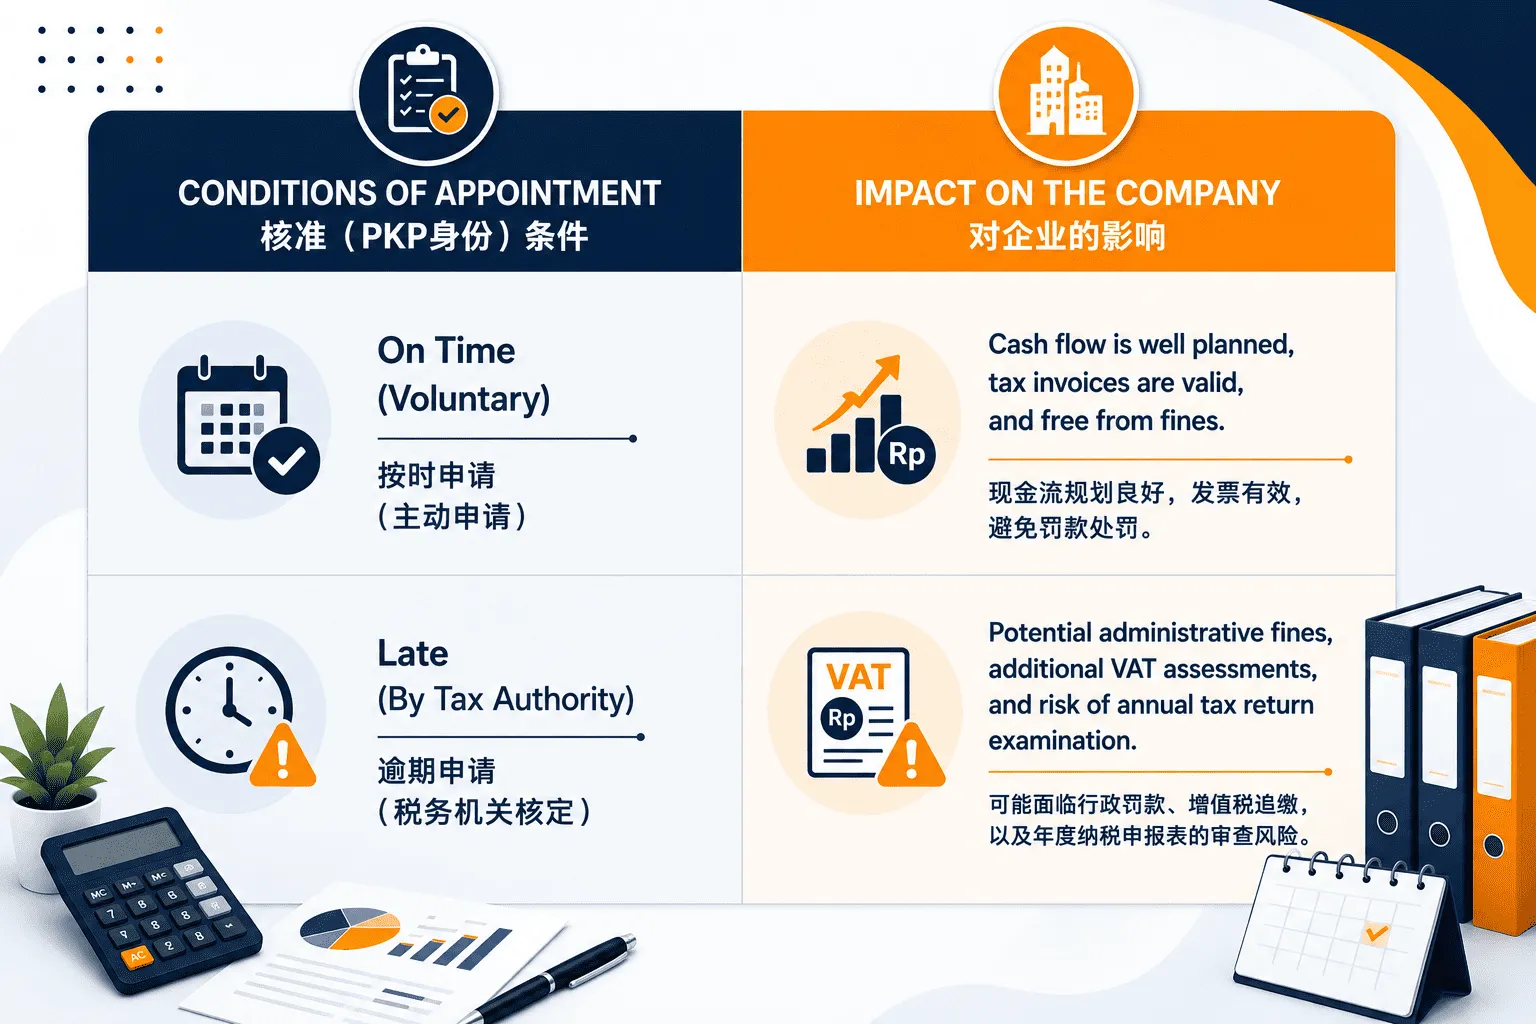
penalties, fines, and additional tax assessments
FAQ About PKP Confirmation
What is the turnover limit that requires a business to become PKP?
The turnover limit is IDR 4.8 billion in one fiscal year in accordance with PMK 197/PMK.03/2013 and PMK 164/2023.
When is the reporting deadline after turnover exceeds IDR 4.8 billion?
The confirmation application must be submitted no later than the end of the fiscal year when the business turnover exceeds that limit.
Can PKP status that has been obtained be revoked?
Yes. PKP revocation can be done upon the Taxpayer's own request (for example, due to consistent turnover decline) or ex-officio by the KPP if the company is inactive, the Virtual Office address cannot be found, or there is indication of misuse of tax invoices.
Secure Your Business Tax Compliance with Awan Kusuma Legalitas
Monitoring turnover movements and managing tax administration requires precision so that the business is not burdened with unnecessary sanctions.
The professional consultant team at Awan Kusuma Legalitas is ready to assist your company in fulfilling comprehensive business legality, ranging from the issuance of basic legalities such as NIB, provision of legal business domicile via Virtual Office, to assistance in submitting PKP Confirmation and Annual SPT reporting.
Want to evaluate your turnover status or need help with PKP confirmation processing? Contact the Awan Kusuma Legalitas Team via WhatsApp now for a free consultation service!