Many business owners, employees, and company management still think that Periodic SPT and Annual SPT are the same tax obligation. In fact, both have different functions, reporting periods, and administrative purposes at the Directorate General of Taxes (DJP).
Misunderstanding this difference risks causing reporting delays that lead to administrative penalty fines. Understanding the difference between Periodic SPT and Annual SPT is very important for every Taxpayer to maintain tax compliance.
What Is SPT (Tax Return)?
SPT or Surat Pemberitahuan (Tax Return) is an official document used by Taxpayers to report tax calculations and payments, tax objects, and assets or obligations in accordance with applicable tax provisions.
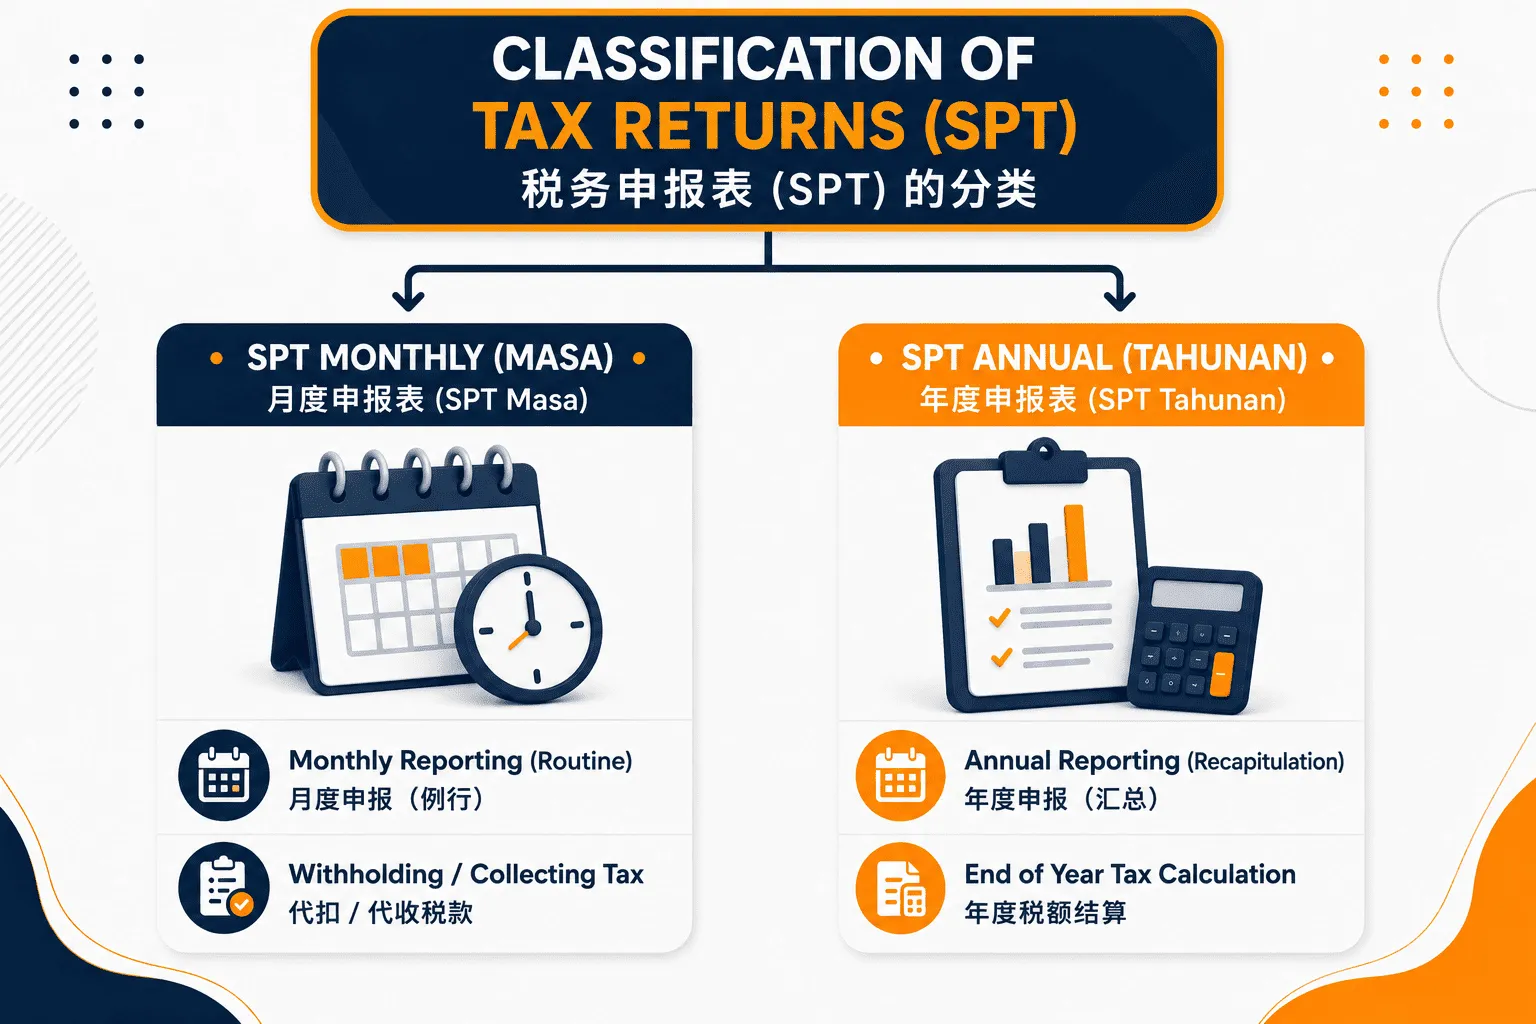
The legal basis regarding SPT is regulated in Minister of Finance Regulation Number 243/PMK.03/2014 concerning Tax Returns. Broadly speaking, SPT classification is divided into two main categories:
Definition & Types of Periodic SPT
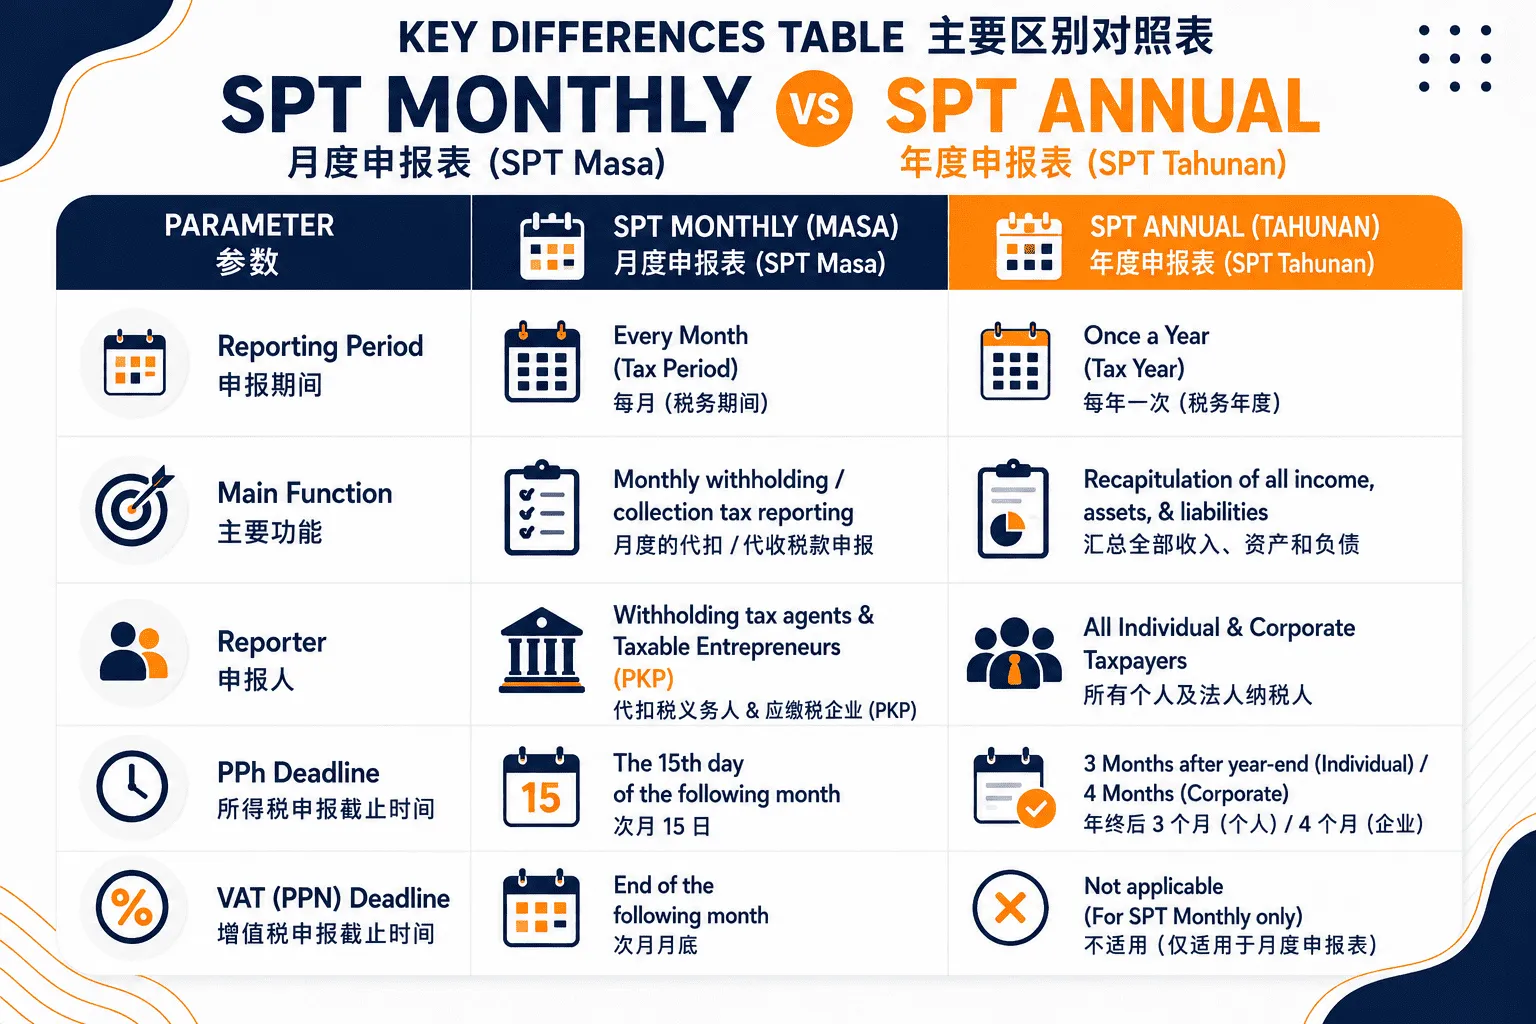
Periodic SPT is a Tax Return used to report tax obligations within one tax period (generally monthly). Through Periodic SPT, Taxpayers report taxes that have been withheld, collected, or remitted on certain transactions.
Several types of Periodic SPT commonly used in business operations:
- Periodic SPT for PPh Article 21/26: Reports income tax withholding on individuals, such as employee salaries or compensation to experts.
- Periodic SPT for Unification PPh: Reports withholding or collection of several types of PPh simultaneously (PPh Article 4 paragraph 2, PPh Article 15, PPh Article 22, and PPh Article 23/26).
- Periodic SPT for VAT: Mandatory report for entities or businesses that have been confirmed as PKP regarding Output Tax and Input Tax.
Definition & Types of Annual SPT
Annual SPT is a Tax Return used to report the entire recap of tax obligations over one tax year. Unlike Periodic SPT, this report includes income accumulation, asset lists, liabilities/debts, and tax credits that have been paid throughout the year.
Types of Annual SPT are divided into:
- Annual SPT for Individuals: Submitted by workers, professionals, or individual business owners.
- Annual SPT for Corporate Entities: Submitted by business entities such as PT Establishment or CV Establishment to report financial performance and Corporate Income Tax calculations.
Comparison Table: Periodic SPT vs Annual SPT
Tax Reporting Deadlines
Knowing reporting deadlines is crucial to avoid administrative penalty fines:
1. Periodic SPT Deadlines
- Periodic SPT for PPh: No later than the 15th of the following month after the tax period ends.
- Periodic SPT for VAT: No later than the end of the following month after the tax period ends.
2. Annual SPT Deadlines
- Annual SPT for Individuals: No later than 3 months after the end of the tax year (March 31).
- Annual SPT for Corporate Entities: No later than 4 months after the end of the tax year (April 30).
Late SPT Reporting Penalties
Based on Article 7 paragraph (1) of the Tax Law (UU KUP) , Taxpayers who are late in submitting SPT are subject to administrative penalty fines of:
- Annual SPT for Individuals: IDR 100,000
- Annual SPT for Corporate Entities: IDR 1,000,000
- Periodic SPT for VAT: IDR 500,000
- Periodic SPT Other Than VAT: IDR 100,000
FAQ About Periodic SPT and Annual SPT
Are Periodic SPT and Annual SPT still required to be reported if they have zero activity?
Yes. In certain conditions, Taxpayers are still required to submit SPT reports even if there are no tax transactions to be paid or the status is zero.
Are all Taxpayers required to report Periodic SPT?
No. Periodic SPT is only required to be submitted by Taxpayers who have withholding/collection obligations or who have been confirmed as Taxable Entrepreneurs (PKP).
Are employees whose taxes have been withheld by the company still required to file Annual SPT?
Yes. PPh Article 21 withholding by the employer does not eliminate the employee's obligation to file an Individual Annual SPT.
Are MSMEs required to report Periodic SPT?
This obligation depends on their licensing status. MSMEs are required to report Periodic SPT if they have been confirmed as PKP or conduct PPh withholding on third parties.
Tax Compliance Assistance Services with Awan Kusuma Legalitas
Managing monthly and annual tax compliance requires precision to avoid fines and administrative sanctions.
The Awan Kusuma Legalitas consultant team is ready to assist with your business tax reporting, starting from PKP (Taxable Entrepreneur) status processing, Periodic SPT assistance, to Annual SPT preparation and reporting.
Want to ensure your business tax reports are submitted on time and free from sanctions? Contact the Awan Kusuma Legalitas Team via WhatsApp now for an integrated tax consultation session!